What is the scope and industry significance of the Automated Window Blinds Market?
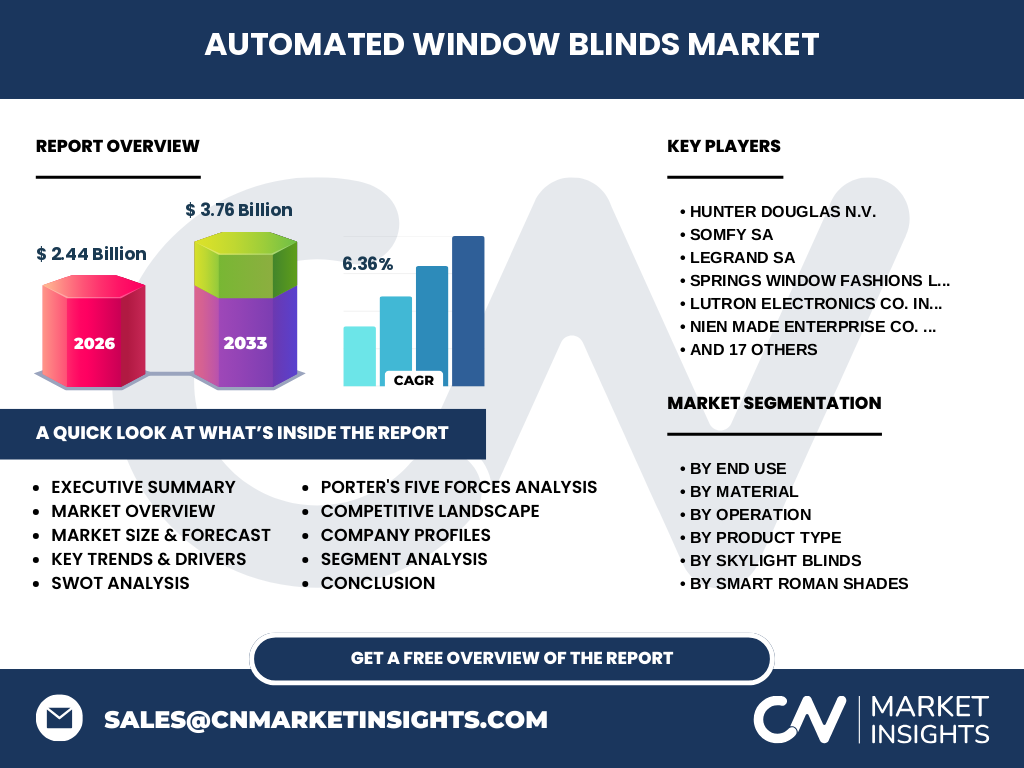
Our analysis indicates that the Automated Window Blinds Market reaches a valuation of $2.44 Billion in 2026, serving a critical role in smart building architecture. Driven by IoT integration, the sector spans residential and commercial spaces, utilizing advanced raw materials like aluminum and PVC to enhance energy efficiency, aligning with strict environmental building codes.
What are the key market drivers, restraints, challenges, and opportunities shaping the Automated Window Blinds Market?
The market is propelled by surging demand for energy-efficient smart homes, though high initial costs for retrofit installations act as a restraint. Supply chain volatility regarding microprocessors for Wi-Fi and battery-powered mechanisms presents ongoing challenges. However, integration with protocols like Zigbee and Matter offers lucrative expansion pathways for manufacturers.
Emerging trends and growth patterns in the Automated Window Blinds Market
The shift toward voice-controlled and solar-powered solutions dominates current adoption curves. Consumers increasingly demand Wi-Fi enabled roller blinds and automated Venetian blinds that interface directly with rooftop photovoltaic systems, significantly lowering operational friction and appealing to eco-conscious commercial developers.
How did the COVID-19 pandemic affect the Automated Window Blinds Market and what is its recovery trajectory?
Pandemic-era supply chain bottlenecks temporarily delayed raw material procurement for aluminum and motorized components. However, subsequent residential renovation booms accelerated home automation adoption. Recovery has outpaced baseline manufacturing projections, stabilizing through robust online retail and specialized installer networks.
Competitive benchmarking and strategic dynamics in the Automated Window Blinds Market
Market concentration is moderately fragmented, featuring established architectural heavyweights alongside agile smart-home pure-plays. Industry leaders continuously leverage proprietary motorization technologies and expand regional distributor partnerships to outpace competitors operating strictly within legacy manual shading segments.
Executive summary of key findings for the Automated Window Blinds Market
Our comprehensive research confirms robust expansion, projecting the market to surge from $2.44 Billion in 2026 to $3.76 Billion by 2033 at a CAGR of 6.36%. Growth is anchored by surging commercial real estate automation and widespread residential smart-ecosystem adoption.
Market forecast trajectory from 2027 to 2033
The data suggests sustained upward momentum, scaling the industry from its 2026 baseline toward the $3.76 Billion forecast by 2033. This steady 6.36% CAGR reflects compounding urbanization rates and mandatory energy-conservation regulations across commercial office complexes.
Segmentation analysis across end use, material, operation, and product type
Segmentation spans multiple dimensions: End Use covers Home, Office, Restaurants And Hotels, Hospitals And Nursing Homes, School And University; Material includes Aluminum, Wooden, and Polyvinyl Chloride; Operation divides into Fully Automatic and Semi Automatic; Product Type features Automated Roller Blinds, Smart Roman Shades, and Motorized Curtains.
Geographic distribution and regional performance across the global landscape
Regional adoption varies heavily based on local smart-infrastructure investments and building regulations. North America and Europe lead in commercial automation integration, while Asia-Pacific exhibits the fastest adoption velocity driven by rapid urban development and rising disposable incomes.
In-depth regional review of high-growth territories
Urban centers in North America and Western Europe demonstrate high concentration of luxury residential retrofits utilizing smart vertical and roller blinds. Meanwhile, developing metropolitan areas in APAC prioritize cost-effective motorized mini blinds and solar-powered skylight solutions to combat intense equatorial solar loads.
Strategic positioning of leading companies in the Automated Window Blinds Market
Industry titans like Hunter Douglas N.V., Somfy SA, and Lutron Electronics Co. Inc. dominate through integrated ecosystem control and premium architectural positioning. Meanwhile, firms like IKEA Group and Tuya Smart capture mass-market volume via accessible, app-compatible retrofit kits.
Porter's Five Forces analysis of competitive pressures
Competitive rivalry is intense, driven by continuous protocol innovation from firms like Crestron and Legrand SA. Bargaining power of suppliers is moderate due to specialized motor components, while the threat of substitutes remains low given distinct convenience advantages over manual window treatments.
SWOT analysis of the Automated Window Blinds Market
Strengths include superior energy efficiency and seamless smart-home integration. Weaknesses center on high upfront unit costs and complex wiring requirements. Opportunities lie in emerging solar-powered variants, while threats involve macroeconomic inflation dampening discretionary home-improvement spending.
Value chain analysis from raw material sourcing to end-user deployment
The value chain initiates with raw material extraction—primarily aluminum, timber, and PVC resins—processed by component manufacturers like Rollease Acmeda. These components flow to assemblers such as WAREMA Renkhoff SE and Draper Inc., before distribution via contractors, installers, and direct online retail.
Investment insights and high-potential strategic expansion areas
Investors should target manufacturers specializing in retrofit-friendly battery and solar-powered configurations, minimizing complex hardwiring hurdles. Companies partnering with major IoT ecosystem providers yield superior scalability compared to hardware-only vendors.
Conclusion and key strategic takeaways for industry stakeholders
The Automated Window Blinds Market represents a high-growth intersection of interior design and IoT technology. Reaching $3.76 Billion by 2033, success favors agile firms that embrace open-source smart home protocols and sustainable material sourcing.
Research methodology behind baseline estimates and market sizing
Our analytical framework triangulates customs trade data, secondary macroeconomic indicators from regulatory bodies, and primary qualitative interviews with C-level executives from key players like Coulisse B.V., Griesser AG, and Nien Made Enterprise Co. Ltd. to ensure robust financial modeling.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing from 2026 through 2033 across specified end-use, material, and operational segments. Limitations include unforeseen geopolitical trade shifts impacting raw material availability and rapid technological obsolescence cycles inherent to the IoT sector.
Recent developments, corporate partnerships, and strategic product launches
Recent market dynamism includes strategic collaborations between automation platforms like Tuya Smart and regional manufacturers such as SmartWings Home LLC and Yoolax to launch Matter-compliant voice-activated shading solutions, reflecting an industry-wide push toward universal interoperability.